Mintos review 2026: is it worth it for European investors?


In this review, we look at Mintos, the Latvian platform best known for investing in loans, which now also sells ETFs, stocks, bonds, real estate, crypto ETPs and a cash product called Smart Cash. We explain what each product is, what it costs, what loan investors actually earned in each year since 2015, how much money is stuck in recovery, how your money is protected and where the real risks are. We have had a Mintos account since 2020, and the screenshots below come from it.
All figures below were checked on Mintos' website, price list, statistics pages, annual reports and help centre on 17 and 18 November 2026.
Overview
Mintos is operated by AS Mintos Marketplace, registered in Riga, Latvia. It is an investment firm licensed and supervised by Latvijas Banka, the central bank of Latvia, and has held its licence since 2021. According to its 2025 annual report, Mintos ended 2025 with €795 million in assets under management and 664,000 clients.
Mintos started in 2015 as a marketplace for loans from lending companies. Today it is closer to an all-in-one investment app, but loans remain the product it is known for and the one that needs the most care.
Highlights
| Metric | Details |
|---|---|
| Company | AS Mintos Marketplace, Riga, Latvia¹ |
| Regulator | Latvijas Banka, MiFID investment firm¹ |
| Investor protection | Up to €20,000 if Mintos fails to return your assets¹ |
| Size | €795 million AUM and 664,000 clients at the end of 2025⁴ |
| Loan net return | From -1.2% (2022) to 12.6% (2016)⁵ |
| Loans in recovery | €188 million, about 26% of loans (18 November 2026)⁶ |
| Products | Loans, bonds, ETFs, stocks, real estate, crypto ETPs, Smart Cash¹ |
| Stocks and ETFs | €0 commission, from €1² |
| Inactivity fee | €4.90/month after 360 days without activity³ |
Sources: (1) Mintos homepage, (2) Mintos price list, (3) help centre: inactivity fee, (4) AS Mintos Marketplace 2025 annual report, (5) Mintos historical performance, (6) Mintos loan statistics. Checked 17 and 18 November 2026.
Pros and cons
Pros
- Licensed MiFID investment firm, supervised by the central bank of Latvia
- Covered by the Latvian investor compensation scheme up to €20,000
- Publishes gross and net loan returns for every year since 2015, including the bad years
- Commission-free ETFs and stocks, from €1
- Free bank deposits and withdrawals
- Many asset types in one account, including loans and bonds that most brokers do not offer
Cons
- Loan investments carry credit risk: in 2022, the average net return on Mintos loans was -1.2%
- About 26% of the money in Mintos loans was in recovery in November 2026, led by €63.5 million from Nera Capital
- The investor compensation scheme does not cover losses from defaults or price changes
- Yearly fees on loan and bond portfolios (0.29% to 0.39%)
- 0.85% fee to sell on the Secondary Market
- €4.90 monthly inactivity fee in some cases
- Mintos itself has been loss-making in 2024 and the first nine months of 2025
Products on Mintos
Loans
Loans are Mintos' original product. You do not lend directly to borrowers: you buy Notes, financial instruments linked to loans issued by lending companies in different countries. There are three ways to invest:
- Core Loans: a ready-made portfolio with automatic diversification. You can cash out at any time
- Custom Loans: your own automated portfolio with the criteria you choose, with liquidity through the Secondary Market
- Manual Loans: you pick individual Notes, filtering by more than 10 criteria
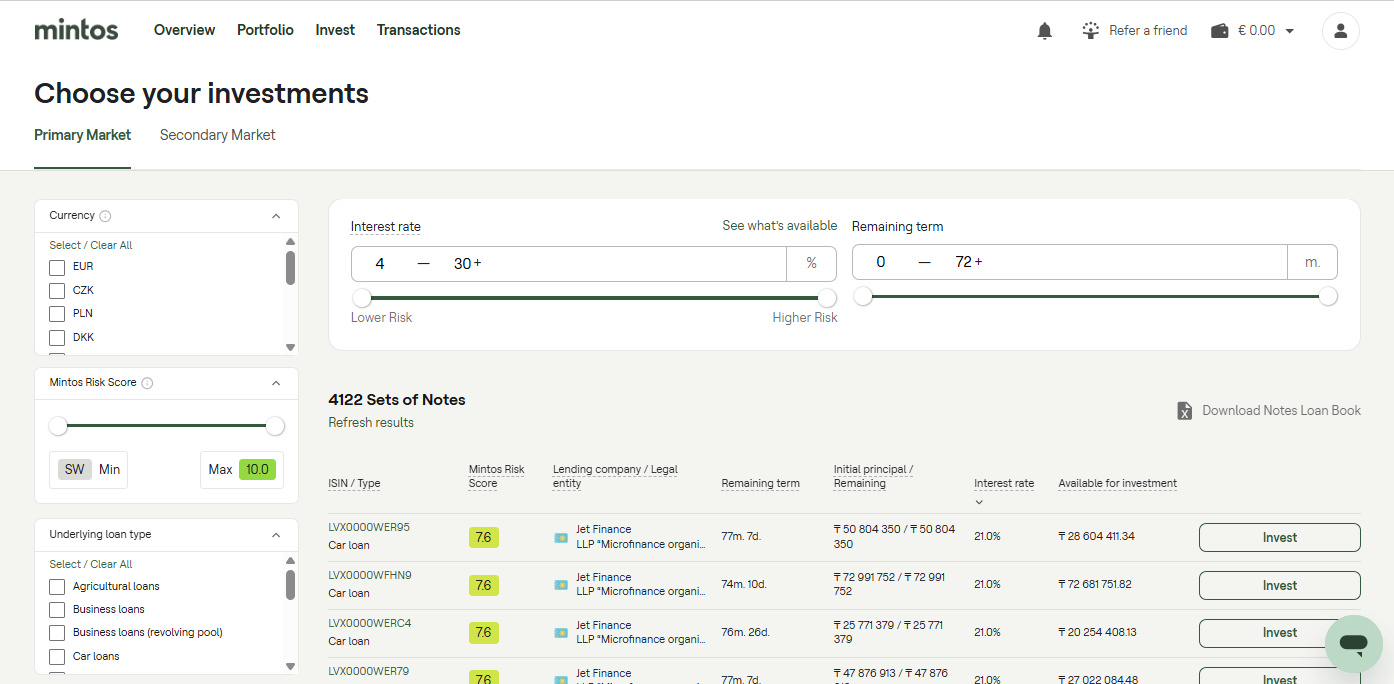
In the Primary Market, you can filter Notes by currency, Mintos Risk Score, loan type, country, interest rate and remaining term. When we checked on 17 November 2026, there were 4,122 sets of Notes. At the top of the list were car loans from Jet Finance in Kazakhstan, paying 21% in Kazakhstani tenge, so an investor in euros would also take currency risk.
Mintos advertises a yield (APY) of 9.2% for Core Loans on its homepage. That figure is not a guaranteed return: it does not account for future defaults or delays by borrowers or lending companies. Mintos publishes a Risk Score for each lending company, which is worth checking before you invest.
ETFs and stocks
Mintos offers commission-free ETFs and stocks, from €1. You can buy them on their own or alongside other products. The ETF list includes the iShares Core S&P 500 (SXR8), the iShares Core MSCI World (EUNL) and the Vanguard FTSE All-World (VWCE). For a broad, long-term portfolio, the ETFs in our VWCE vs IWDA comparison are a common starting point.
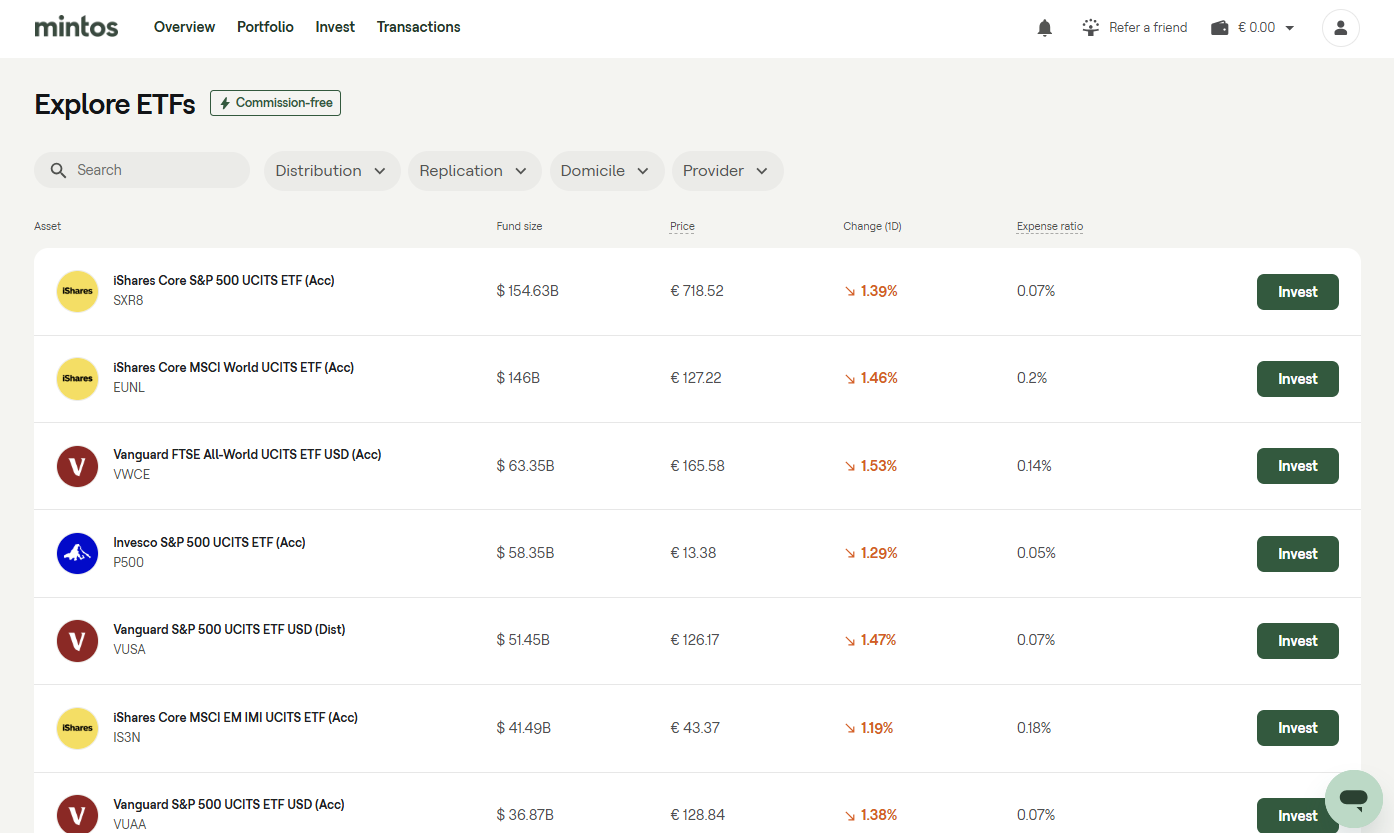
Each ETF page states that there are no order, custody, inactivity or withdrawal fees, only the expense ratio built into the ETF's price. ETFs and stocks are only available in some countries, and Mintos confirms availability once your identity is verified.

Bonds
You can buy high-yield corporate bonds individually or through an automated High-Yield Bonds portfolio, from €50. High-yield bonds pay more interest because the issuers carry more risk of not paying, and that risk is real on Mintos too: the bonds of Easy Debt Service, a Lithuanian debt-collection company, have missed coupon and principal payments (see the recovery section below).
Smart Cash, real estate and crypto
- Smart Cash invests uninvested cash in money market funds. Mintos showed a 2.5% yield on its homepage, before the 0.19% yearly fee
- Real estate gives exposure to rental income and property value, without owning a property directly
- Crypto ETPs track crypto prices from €5, without wallets or keys
When we checked, the real estate Primary Market listed four rental apartments in Latvia, with expected annual returns of 8.59% to 9.29% and monthly interest payments. Expected returns are not guaranteed.

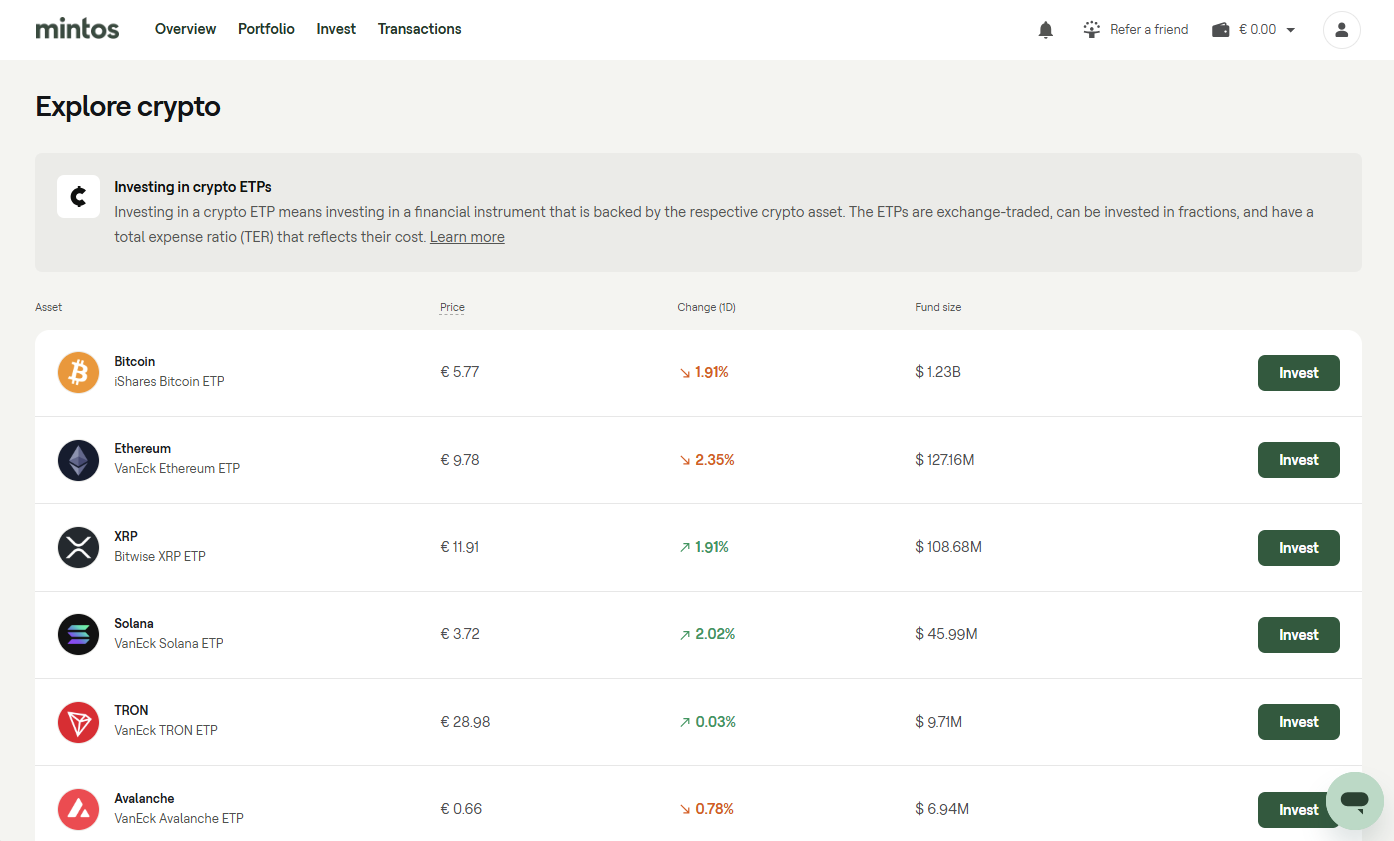
The crypto ETPs come from issuers such as iShares, VanEck and Bitwise, and cover Bitcoin, Ethereum, XRP, Solana and other coins.
Minimum investment
| Product | Minimum |
|---|---|
| Loans, Primary Market | €50 per set of Notes |
| Bonds and real estate, Primary Market | €50 |
| Secondary Market (loans, bonds, real estate) | €1 |
| ETFs and stocks | €1 (€50 for the Core ETFs portfolio) |
| Smart Cash | €1 |
| Crypto ETPs | €5 |
Sources: Mintos help centre on minimum amounts and ETF minimums, and the Mintos homepage. Checked 18 November 2026.
The €50 minimum per set of Notes matters for diversification: spreading a manual loan portfolio over 20 lending companies takes at least €1,000.
What Mintos loan investors actually earned
This is the question that matters most: how much did loan investors really make after defaults? Mintos publishes two figures for each year. The gross return is the interest before fees and losses. The net return subtracts the losses, including write-offs on loans from suspended lending companies, based on Mintos' recovery estimates.
| Year | Net return | Gross return |
|---|---|---|
| 2024 | 9.3% | 9.3% |
| 2023 | 10.4% | 10.4% |
| 2022 | -1.2% | 7.1% |
| 2021 | 6.1% | 9.7% |
| 2020 | 4.3% | 10.6% |
| 2019 | 11.0% | 11.5% |
| 2018 | 12.1% | 12.1% |
| 2017 | 11.6% | 12.1% |
| 2016 | 12.6% | 12.6% |
| 2015 | 12.0% | 12.0% |
Source: Mintos historical performance, checked 17 November 2026. Averages for all loans on Mintos, weighted by outstanding investment. Net figures are updated every quarter.
Three things stand out:
- Losses come in bad years: Mintos itself links 2020 to the Covid-19 effect and 2022 to losses related to the war between Russia and Ukraine. In 2022, losses wiped out all the interest and more
- Over 2020 to 2024, the average was about 5.7% per year (our calculation, compounding the net returns above), well below the advertised yields of 9% to 10%
- Recent years can still change: net returns for 2023 and 2024 match the gross returns today, but Mintos updates net figures every quarter with its latest recovery estimates
These are averages across all Mintos loans. Your own return depends on which loans and lending companies you hold. Mintos shows your personal net annualised return in your account.
Funds in recovery: Nera Capital and other cases
When a lending company stops paying, the money moves to "in recovery" while Mintos tries to get it back. On 18 November 2026, Mintos' loan statistics showed €188.0 million in these ongoing cases, against about €544 million in loans from lending companies that are still active. In other words, about 26% of the money in Mintos loans was in recovery. A further €12.4 million had already been written off as bad debt.
| Lending company | In recovery | Days in recovery |
|---|---|---|
| Nera Capital (Ireland, UK litigation loans) | €63.5 million | 224 |
| Russian lending companies (Kviku, Dozarplati, Lime Zaim, EcoFinance, Creditter) | €52.5 million | About 1,700 |
| MFO FintechFinance (Kazakhstan) | €22.3 million | 179 to 196 |
| Wowwo (Turkey) | €18.5 million | 1,798 |
| GetBucks (Botswana, Zambia) | €8.8 million | 2,314 to 2,448 |
| Finko (Armenia) | €6.3 million | 2,280 |
Source: Mintos loan statistics (Loan Performance Details, overdue ongoing cases), checked 18 November 2026. Our sums per lending company group. Days in recovery are Mintos' averages.
Nera Capital is the largest case. Mintos investors financed loans to UK law firms that fund consumer claims, through Nera Notes. In 2026, Mintos said the lending company had no funds to pay interest while the UK Solicitors Regulation Authority reviewed the law firms, and the first larger principal repayment, due on 20 May 2026, was not paid (Mintos update). Since then, Mintos has been negotiating a restructuring.
The Russian lending companies have been in recovery for about 1,700 days, since the restrictions on transfers out of Russia that followed the invasion of Ukraine in 2022.
FintechFinance and Biznes Zaim were removed from the Primary Market in 2026 and lost their Mintos Risk Score. In June 2026, Mintos said the proposed repayment period was about 18 to 24 months, with the final timeline still to be agreed (Mintos update).
Easy Debt Service shows that bonds are not exempt. After missed coupon and principal payments, Mintos issued an Event of Default notice and, in October 2026, moved to the enforcement stage (Mintos delayed bond payments).
Money in recovery is not lost yet, and some cases end well: in 2021, Mintos recovered all the money owed by Aforti in Poland. But recoveries can take years, and during that time you cannot use the money. If you invest in loans, check how much of a lending company's Notes are already overdue and avoid putting a large share into any single one.
Our own Mintos account
We opened our Mintos account in 2020 and invested in loans. The account value peaked at about €530 that year, and the fall that follows in the chart is a withdrawal we made, not a loss. Today, €27.74 is still invested in loans, and the portfolio page shows a total return of €40.53 on our loans.
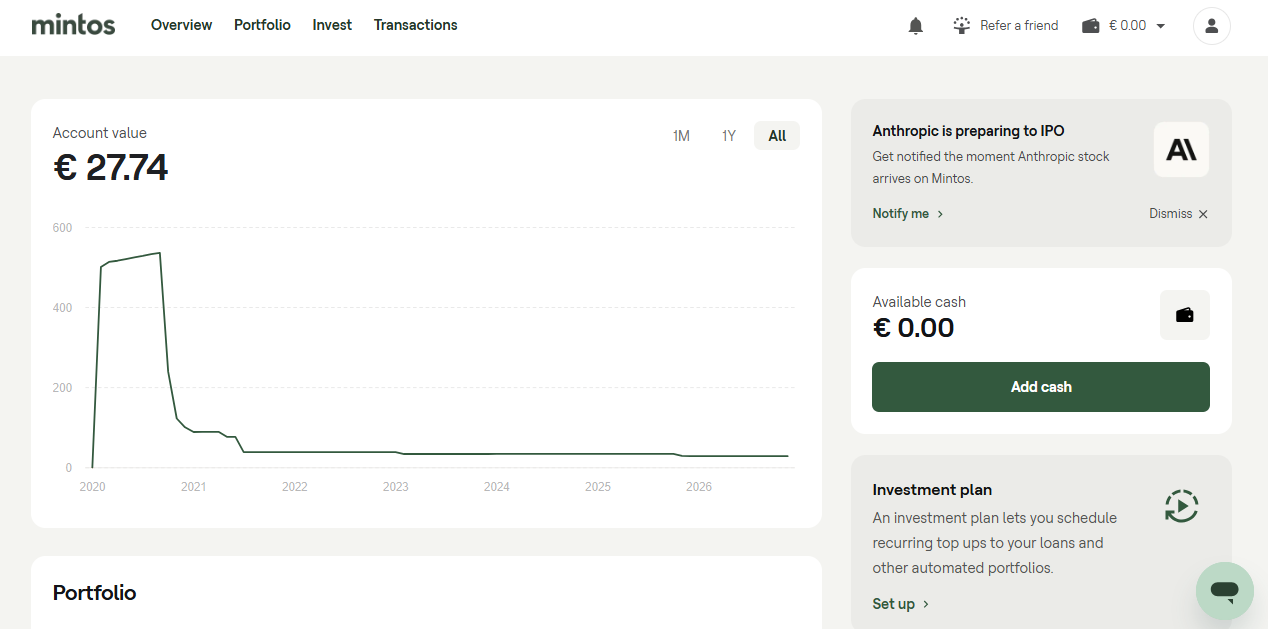
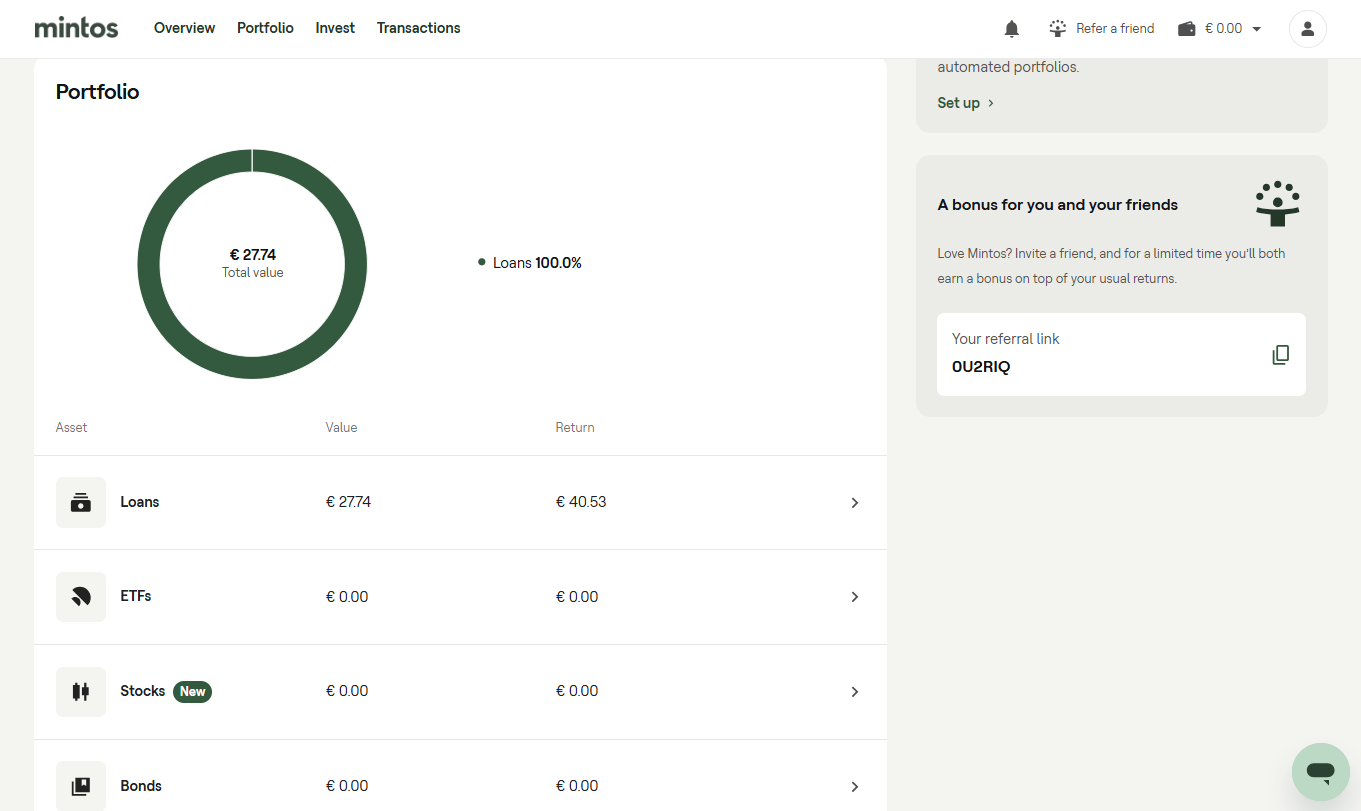
The €27.74 left in loans comes back very slowly. In June, July and August 2025, one loan returned €0.06, €0.01 and €0.04 of principal through buybacks. Meanwhile, because we had not invested, deposited, sold or withdrawn for more than 360 days, Mintos charged its inactivity fee. Between 1 January 2025 and 17 November 2026, the fee took €5.56, which was all the cash left in the account. Our loans did not exempt us from the fee, because the exemption only covers ETFs, bonds, Smart Cash and real estate.
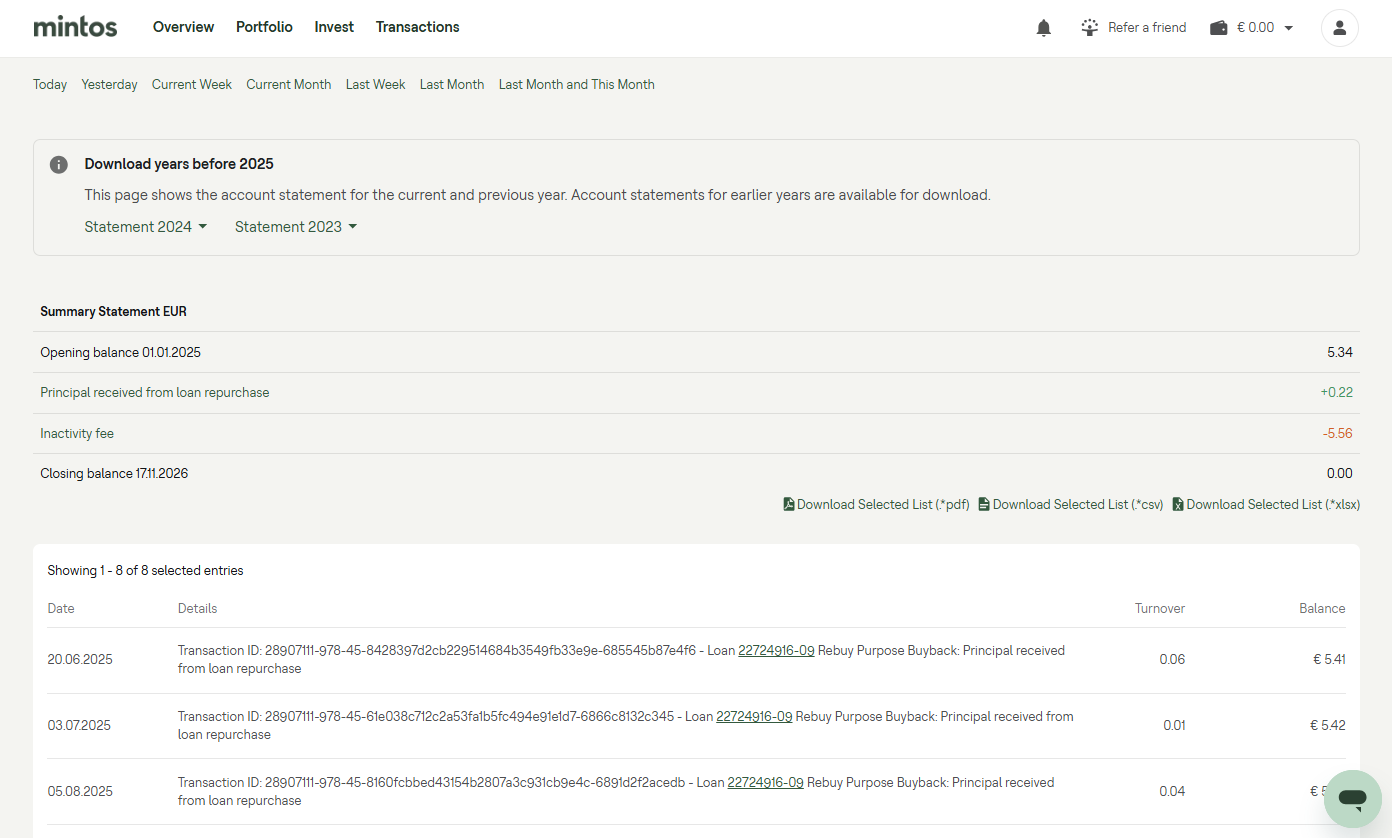
The lesson: if you stop using Mintos, do not leave a small loan balance behind. Sell what you can, withdraw your cash, or move it into a product that is exempt from the inactivity fee.
Fees
| Fee | Amount |
|---|---|
| ETFs, stocks, manual loans, real estate | Free to invest |
| Core Loans, High-Yield and Conservative portfolios | 0.39% per year |
| Custom Loans portfolios | 0.29% per year |
| High-Yield Bonds portfolio | 0.39% per year |
| Smart Cash | 0.19% per year, charged monthly |
| Crypto ETPs | 0.49% per transaction, min €0.99 |
| Secondary Market | 0.85% when you sell |
| Currency exchange | From 0.50% |
| Card, Apple Pay, Google Pay deposits | 2% of the amount |
| Bank deposits and withdrawals | Free |
| Inactivity | €4.90 per month |
Source: Mintos price list, checked 17 November 2026.
The inactivity fee applies after 360 days without depositing, investing, selling or withdrawing. Mintos' cost examples state that investors with active investments in ETFs, bonds, Smart Cash or real estate are excluded, and the fee is not collected if your balance is below €4.90 (help centre). In practice, it mainly affects investors who left a small loan portfolio untouched, as happened in our own account.
Deposits, withdrawals and app
You add money by bank transfer, card, Apple Pay or Google Pay. Bank transfers are free, while card and wallet deposits cost 2% of the amount. Withdrawals to a bank account are free. According to Mintos, euros sent to a bank that supports SEPA Instant usually arrive in about 30 minutes, and other withdrawals usually take 1 to 2 business days (help centre). Money you take out of Smart Cash is usually back in your Mintos account on the same day.
Besides the website, Mintos has an app on the App Store and Google Play.
Taxes on Mintos
Mintos is based in Latvia, so it applies Latvian withholding tax to some of the income of private investors. Tax rules depend on your country of residence, so treat this as a general overview:
- Withholding tax on Notes and Fractional Bonds: Mintos deducts tax from the interest on Notes (loans and real estate) and on Fractional Bonds. For tax residents of EU or EEA countries other than Latvia, the rate is 5% once you confirm your tax residency. Otherwise, a rate of up to 25.5% can apply. Companies pay no withholding tax
- No withholding tax on Smart Cash, ETFs and bonds held directly, according to Mintos' tax guides
- You still declare the income at home: you report the gross interest in your country of tax residence and can usually deduct the tax withheld in Latvia under the double tax treaty. Mintos issues a tax statement that serves as proof
- Losses rarely help: Mintos' guides note that losses on interest income are usually not deductible
Sources: Mintos help centre on tax withholding and its general EU tax guide, checked 18 November 2026. This is not tax advice.
Is Mintos safe?
Two different risks need to be kept apart:
- The risk that Mintos itself fails. Mintos is a licensed investment firm. Your cash and securities are held separately from Mintos' own assets, and the Latvian investor compensation scheme pays up to €20,000 if Mintos cannot return your financial instruments or cash
- The risk that your investments lose value. The scheme does not cover losses from changes in price or liquidity, nor from defaults by borrowers or lending companies. This risk stays with you
On the company side, Mintos' own investor presentation shows a net profit of €650,000 in 2023, then a net loss of €2.7 million in 2024 and €2.2 million in the first nine months of 2025, as it spent on new products. Its accounts are audited by KPMG Baltics (investor relations). Losses at the company level do not touch your segregated assets, but they are worth following.
For ETFs, stocks and Smart Cash, the risks are similar to those at any broker. For loans and high-yield bonds, the credit risk of the lending companies and issuers is the main risk.
The risks of investing in loans
- Lending company risk: if a lending company gets into trouble, payments can stop and recovery can take years
- Country and currency risk: many lending companies operate outside the euro area, and the 2022 losses came from a war
- Liquidity: outside Core Loans, you sell through the Secondary Market, where you may need to accept a discount and pay a 0.85% fee
- Advertised yields are not returns: as the table above shows, net returns have been far below the gross yield in bad years
A common approach is to keep loans to a small part of a portfolio, with the core in broad ETFs. If you mainly want a return on cash, a savings account is simpler: see our list of the best savings accounts in Europe.
Mintos alternatives
Two loan platforms come up most often next to Mintos. Both are simpler, but neither mentions on its website what sets Mintos apart: an investment firm licence and an investor compensation scheme.
| Platform | Advertised return | Company | Compensation scheme |
|---|---|---|---|
| Mintos | 9.2% (Core Loans) | AS Mintos Marketplace, Latvia | Up to €20,000 |
| Go & Grow (formerly Bondora) | Up to 6% per year | Go&Grow OÜ, Estonia | Not mentioned |
| PeerBerry | Up to 11% | Peerberry d.o.o., Croatia | Not mentioned |
Sources: Go & Grow and PeerBerry websites, checked 18 November 2026. Advertised returns are not guaranteed.
Go & Grow is the simplest: one product, from €1, with a €1 fee per withdrawal. Its own website describes it as a consumer loan receivables service, not a bank deposit or a regulated investment service. PeerBerry says all its loans come with a buyback guarantee, under which the lending company buys back a loan if the borrower is more than 60 days late. A buyback guarantee is only as strong as the lending company behind it, which is exactly what failed in the Mintos cases above.
Who is Mintos for?
Investors who want loans and bonds next to ETFs: few EU platforms combine all of them in one regulated account.
Investors who understand credit risk: the loan products suit people who accept that some lending companies can fail, and that a year like 2022 can wipe out the interest, and who diversify across many lending companies.
Who Mintos is not for
- Investors who want a guaranteed return or a savings account replacement
- Investors who only want ETFs: a low-cost broker does the same job without loan-related fees
- Investors who plan to deposit once and forget the account, because of the inactivity fee
Final verdict: is Mintos worth it in 2026?
Mintos has become a regulated, broader investment platform, with free ETF and stock trades and protection up to €20,000 if the company fails. It is also one of the few loan platforms that publishes net returns for every year, which lets you judge it on results rather than advertised yields.
Those results are the reason for caution. Loan investors earned 11% to 12.6% in the early years, but only about 5.7% per year on average from 2020 to 2024, with a loss in 2022. In November 2026, about 26% of the money in Mintos loans was also in recovery, including €63.5 million from Nera Capital, so the net returns of recent years may still fall. If you invest in loans on Mintos, keep it to a small share of your portfolio and diversify across many lending companies. For ETFs alone, our list of the best European brokers for ETFs offers simpler options.
Frequently asked questions
Is Mintos regulated?
Yes. AS Mintos Marketplace is an investment firm licensed and supervised by Latvijas Banka, the central bank of Latvia, and can offer its services across the EU.
Is my money protected on Mintos?
If Mintos fails to return your financial instruments or cash, the Latvian investor compensation scheme covers up to €20,000. It does not cover losses from defaults or price changes.
What returns did Mintos investors get?
According to Mintos, the average net return on loans was 9.3% in 2024, 10.4% in 2023, -1.2% in 2022, 6.1% in 2021 and 4.3% in 2020. The figures for recent years can still change as Mintos updates its recovery estimates.
How much money is in recovery on Mintos?
On 18 November 2026, Mintos' statistics showed €188 million in recovery, about 26% of the money in loans. The largest case was Nera Capital, with €63.5 million.
What is the minimum investment on Mintos?
€1 for ETFs, stocks, Smart Cash and Secondary Market purchases, and €50 per set of Notes on the Primary Market.
Does Mintos withhold tax?
Yes, on the interest from Notes and Fractional Bonds. Tax residents of EU or EEA countries other than Latvia pay 5% once they confirm their tax residency, and still declare the gross interest in their own country.
Does Mintos charge fees?
ETFs, stocks, manual loans and real estate are free to invest in. Loan and bond portfolios cost 0.29% to 0.39% per year, selling on the Secondary Market costs 0.85% and there is a €4.90 monthly inactivity fee in some cases. Our own account paid €5.56 of inactivity fees on a small loan balance.
Is the 9.2% Mintos yield guaranteed?
No. It is the advertised yield on Core Loans and does not include future defaults. Net returns have been far lower in bad years.
Disclaimer: This article is for informational purposes only and does not constitute financial advice. Investing involves risk, including the potential loss of your invested capital. Past performance and advertised yields do not guarantee future returns. Fees may change: check Mintos' website before you invest.